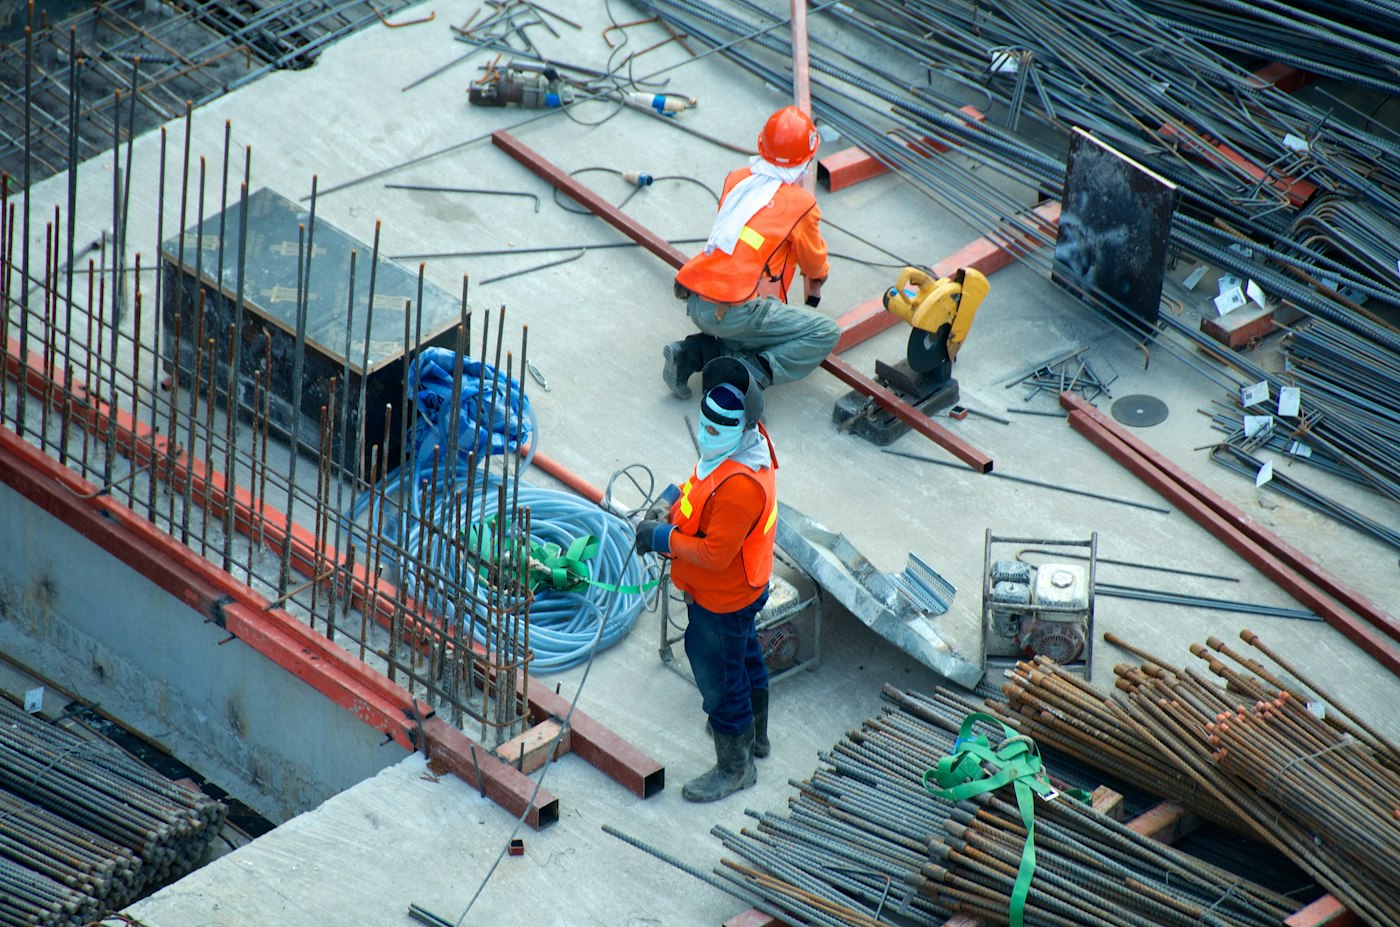
Every year, approximately 2.6 million nonfatal workplace injuries and illnesses are reported by private industry employers, according to the Bureau of Labor Statistics. Workers' compensation provides a critical safety net — but claims are frequently denied, delayed, or undervalued without proper legal guidance.
What Workers' Compensation Covers
Workers' comp is a no-fault insurance system that provides benefits for employees injured on the job, regardless of who caused the accident. Coverage typically includes:
- Medical expenses — All reasonable and necessary treatment related to the injury
- Temporary disability — Wage replacement (typically 60–70% of your average weekly wage) while you cannot work
- Permanent disability — A lump sum or structured payments if the injury causes lasting impairment
- Vocational rehabilitation — Job retraining if you cannot return to your previous occupation
- Death benefits — Compensation to dependents if the injury results in death
What Workers' Comp Does NOT Cover
- Pain and suffering (unlike personal injury lawsuits)
- Full wage replacement (typically capped at 60–70%)
- Injuries caused intentionally by the employee
- Injuries sustained while under the influence of drugs or alcohol
- Independent contractors in most states (though misclassification is common)
The Workers' Compensation Claims Process
Step 1: Report the Injury Immediately Notify your supervisor as soon as possible. Most states require written notice within 30 days, and some require it within as few as 5 days. Missing this deadline can forfeit your claim.
Step 2: Seek Medical Treatment In most states, your employer or their insurance carrier has the right to direct you to a specific authorized physician for initial treatment. Follow your employer's protocol exactly to avoid jeopardizing your claim.
Step 3: File the Claim Your employer is required to file a First Report of Injury with their workers' comp insurer. Follow up to confirm this has been done.
Step 4: The Insurance Company Investigates The insurer has 14 to 30 days (varies by state) to accept or deny your claim. Common denial reasons include: reporting delay, disputed injury cause, or pre-existing conditions.
Step 5: Receive or Appeal Benefits If accepted, benefits begin. If denied, you have the right to appeal through your state's workers' compensation board.
Average Workers' Comp Settlements
| Injury Type | Average Settlement |
|---|---|
| Back injury | $40,000 – $80,000 |
| Carpal tunnel / repetitive strain | $30,000 – $70,000 |
| Leg / knee injury | $50,000 – $100,000 |
| Traumatic brain injury | $100,000 – $500,000+ |
| Occupational disease | $50,000 – $200,000 |
Settlements are typically reached as a lump sum through a process called a Compromise and Release or a Stipulated Award.
Your Third-Party Lawsuit Rights
If your workplace injury was caused by someone other than your employer — such as a negligent equipment manufacturer, a subcontractor, or a reckless driver — you may be able to file a third-party personal injury lawsuit in addition to your workers' comp claim. This allows you to recover damages including pain and suffering that workers' comp does not provide. Speak with an attorney in our directory to evaluate all your options.
Common Mistakes That Hurt Your Claim
- Delaying reporting the injury
- Failing to follow the authorized treating physician's instructions
- Missing medical appointments
- Returning to work before you are medically cleared
- Posting on social media about physical activities
- Accepting a quick settlement before understanding the full extent of your injuries
When to Hire a Workers' Compensation Attorney
Consider consulting an attorney if your claim is denied, your benefits are delayed, your employer retaliates against you for filing, or your injuries are serious and long-term. Most workers' comp attorneys work on contingency at rates set by state law, typically 10–20% of recovery.
Frequently Asked Questions
Q: Can I be fired for filing a workers' compensation claim? A: No. Retaliation for filing a workers' comp claim is illegal in all 50 states. If your employer fires you, demotes you, or otherwise retaliates, you may have additional legal claims. Contact an employment attorney immediately.
Q: What if my employer does not have workers' compensation insurance? A: All states except Texas require most employers to carry workers' comp. If your employer is uninsured, most states have an Uninsured Employers Fund to pay your benefits. You may also sue your employer directly.
Q: Can I choose my own doctor for a work injury? A: This varies by state. About half of states allow the employer or insurer to direct initial medical care. After a certain period or under specific circumstances, you may have the right to see your own physician.
Q: Does workers' comp cover stress and mental health injuries? A: Increasingly yes. Mental health conditions caused by workplace stress or trauma are covered in many states, though the standards are higher than for physical injuries.
Q: How long can I collect workers' compensation benefits? A: Temporary total disability benefits typically last until you return to work or reach maximum medical improvement (MMI). Permanent disability benefits can continue for years or even lifetime depending on severity and state law.
MyLegalWin Directory
Need Legal Help
With Your Case?
Browse attorneys by practice area and location, review their profiles, and choose whom to contact.